
 Creditkeeda

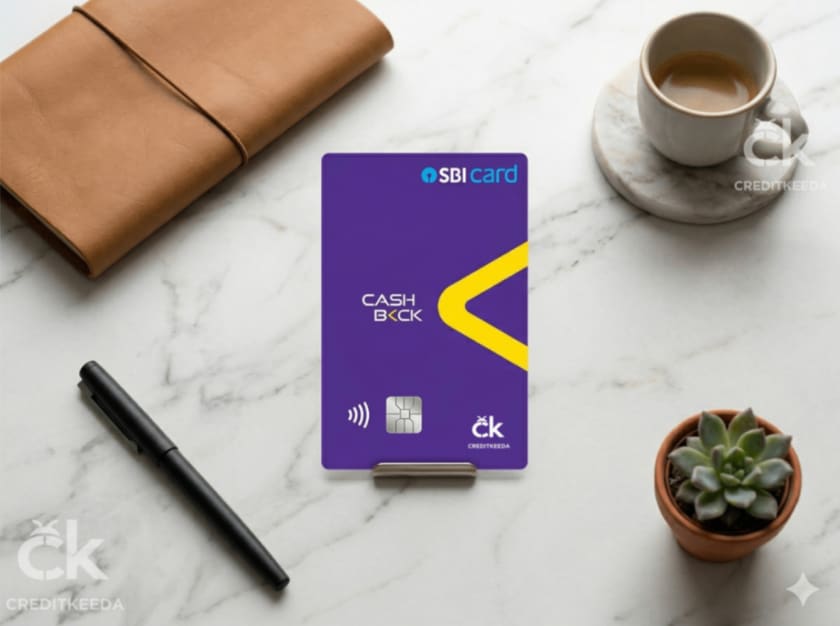
The SBI Cashback Credit Card remains one of the most compelling cashback cards in India for online spending. However, the April 2026 devaluation has reduced its earning potential, especially for high spenders. While casual and moderate users will continue to extract strong value, aggressive optimisers will find the new caps restrictive.
Is the SBI Cashback Card still the undisputed king of your wallet, or is it time to downgrade? Here is our complete 2026 breakdown.
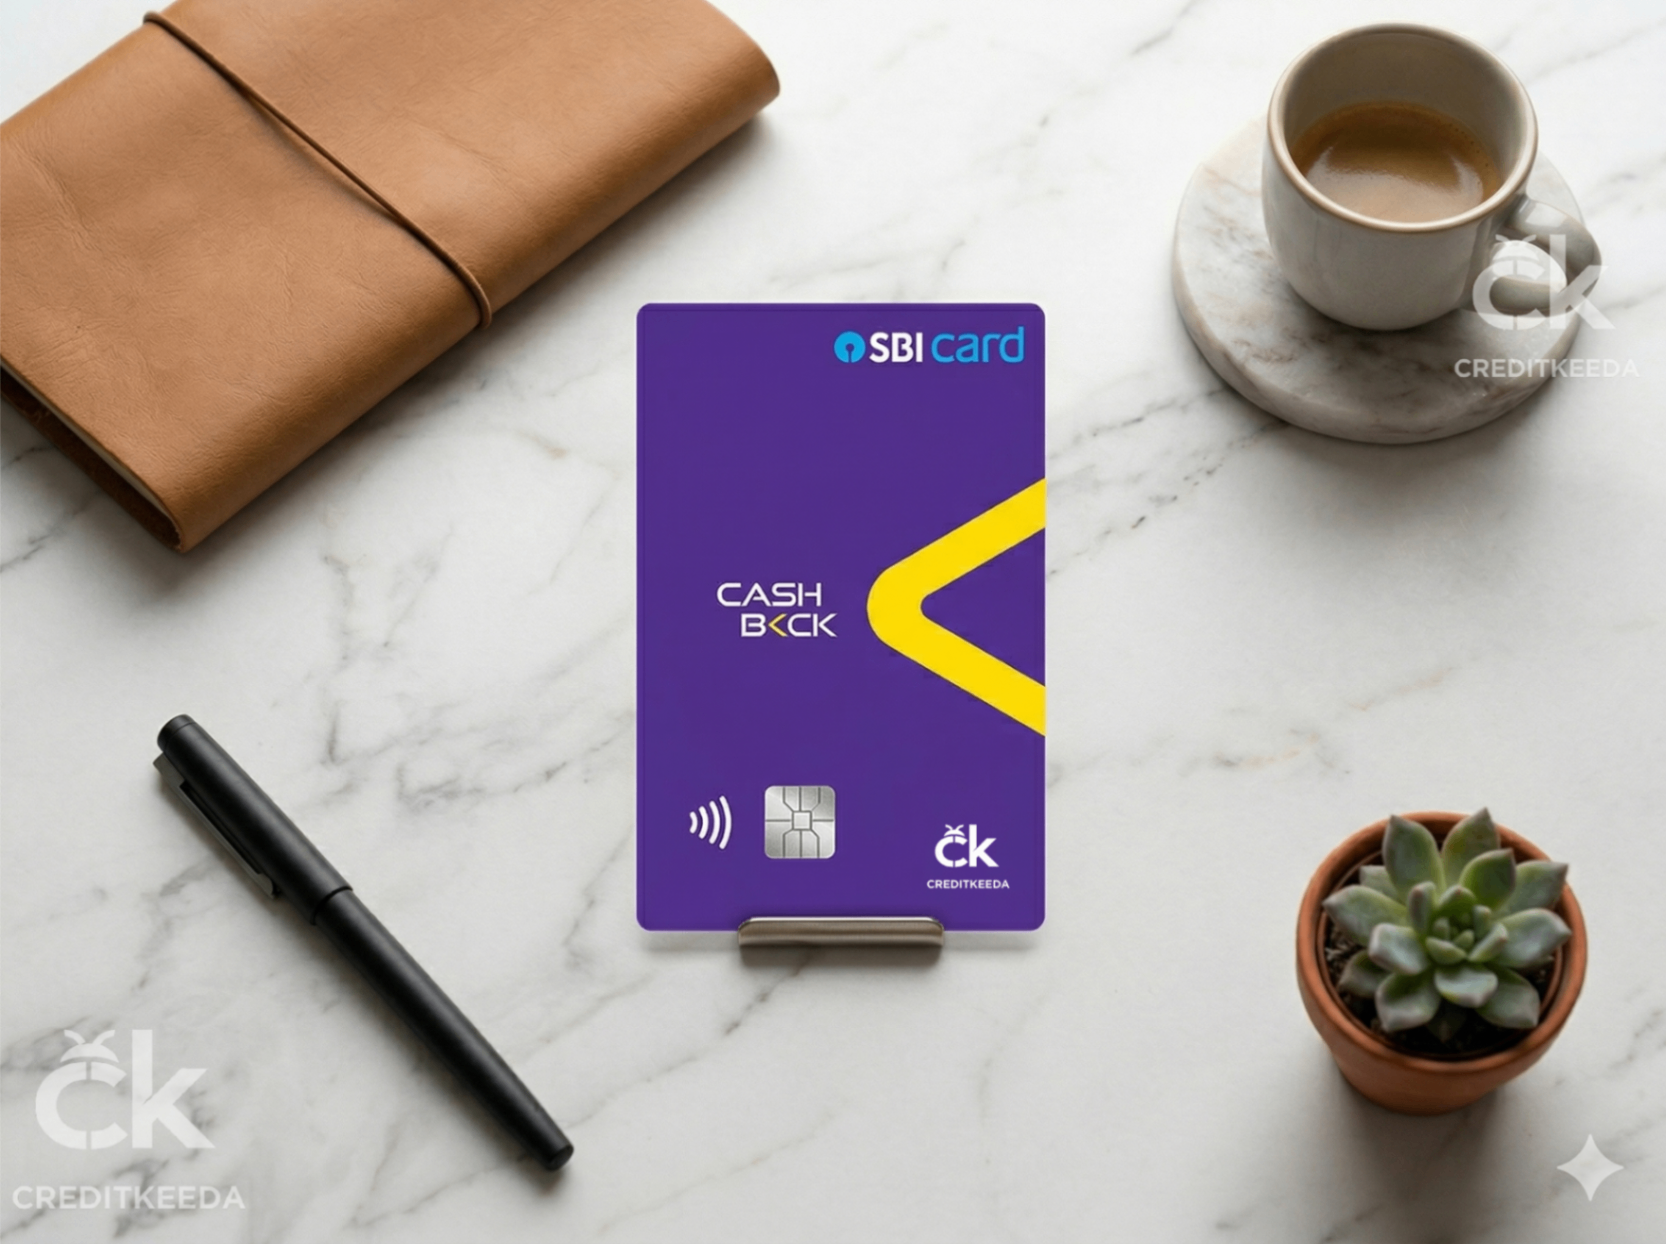
Card Overview
Feature | Details |
|---|---|
Issuer | SBI Card |
Network | Visa |
Joining Fee | ₹999 + GST |
Annual Fee | ₹999 + GST (waived on ₹2L annual spend) |
Online Cashback | 5% (capped at ₹2,000/month from Apr 2026) |
Offline Cashback | 1% (capped at ₹2,000/month) |
Total Monthly Cap | ₹4,000 |
Cashback Credit | Auto-credited within 2 working days |
Lounge Access | None |
Fuel Surcharge Waiver | 1% (₹500–₹3,000 transactions) |
Recommended CIBIL | 750+ |
How the Cashback Structure Works
The SBI Cashback Card follows a straightforward model:
5% cashback on online transactions
1% cashback on offline transactions
There are no reward points, no redemption process, and no expiry concerns. Cashback is credited to your statement within 2 working days of billing.
Example:
₹20,000 online spend → ₹1,000 cashback
₹5,000 offline spend → ₹50 cashback
The classification depends on Merchant Category Codes (MCC), not whether the transaction appears “online” to you. Most major platforms—Amazon, Flipkart, Swiggy, Zomato, Myntra, and travel portals—qualify for 5%.
April 2026 Devaluation: Key Changes
Parameter | Before April 2026 | After April 2026 |
|---|---|---|
Total Monthly Cap | ₹5,000 | ₹4,000 |
Online Cashback Cap | No limit | ₹2,000 |
Offline Cashback Cap | No limit | ₹2,000 |
Government Payments | Eligible | Excluded |
Toll Payments | Eligible | Excluded |
Digital Gaming | Eligible | Excluded |
What This Means
₹40,000 online spend now fully exhausts the ₹2,000 cap
Remaining cashback requires offline spending, offering a mere 1% return, which defeats the purpose of holding a premium cashback card.
Realistic monthly cashback potential drops to ₹2,000–₹2,500
For most users, the impact is moderate. For heavy spenders, it is significant.
Cashback Exclusions
The exclusions list continues to expand. The following categories earn zero cashback:
Rent payments
Fuel transactions
Utility bills (direct payments)
Insurance premiums
Wallet loads (Paytm, PhonePe)
Education fees
EMI transactions
Jewellery purchases
IRCTC bookings
Gift cards (officially excluded)
Government payments and taxes
Toll payments
Digital gaming platforms
Cash advances and balance transfers

Fees and Charges
Charge | Amount |
|---|---|
Joining Fee | ₹999 + GST |
Annual Fee | ₹999 + GST |
Interest Rate | 3.5% per month (42% annually) |
Cash Advance Fee | 2.5% or ₹500 |
Forex Markup | 3.5% |
Cost vs Value
₹40,000 monthly online spend = ₹2,000 cashback
Annual cashback = ₹24,000
Annual fee = ₹999 + GST
This yields a net positive value of ~₹22,821 per year, meaning the card pays for itself within the first month for active users.
Practical Ways to Maximise Cashback
These strategies are widely used by experienced cardholders:
1. Convert Utility Payments into Cashback
Buy Amazon Pay vouchers (5% cashback) from a third-party gift card portal
Use balance to pay bills
Effectively converts 0% → 5% category
2. Stack Discounts via CRED or other third-party gift card portals
Buy discounted brand vouchers
Pay using SBI Cashback card
Combined savings can exceed 15–18%
Note: While purchasing vouchers via third-party platforms currently yields cashback based on the platform's merchant category, SBI officially excludes direct gift card purchases. Bank loopholes can close, so monitor your statement credits
3. Increase Credit Limit
Transfer limit from other SBI cards via customer care
Helps avoid hitting limits mid-cycle
4. Instant Limit Reset via YONO
Pay the bill through YONO SBI
Credit limit restores almost instantly
5. Annual Fee Reversal Strategy
Call after the fee is charged
Many users get waivers or retention offers
Pros and Cons
Pros
5% cashback across almost all online platforms
No redemption process
Cashback auto-credited
Wide acceptance
Annual fee waiver achievable
Simple structure
Cons
₹2,000 monthly cap on online cashback
No lounge access
No welcome benefits
Increasing exclusions
Low initial credit limits
History of devaluations
Who Should Get This Card
Ideal for:
₹20K–₹40K monthly online spenders
Users who prefer simplicity over reward optimisation
Multi-platform shoppers (Amazon, Myntra, Swiggy, travel)
Not ideal for:
High spenders (>₹50K/month online)
Travel-focused users (no lounge access)
Utility-heavy spenders
Alternative Cards to Consider
If the SBI Cashback card's new caps and exclusions limit your earning potential, consider these alternatives to fill the gaps or replace it entirely:
SBI PhonePe Select: The Utility Upgrade
Key Benefit: Matches the 5% online return, but adds a massive 10% reward rate on utilities and insurance via PhonePe (where the SBI card gives 0%), plus UPI integration and lounge access.
The Catch: Slightly higher annual fee of ₹1,499.
Verdict: A perfect complement for utility bills, or a direct switch if you want broader benefits and don't mind the fee.
Equitas Selfe: The Offline & Custom Gap-Filler
Key Benefit: Lets you choose two specific categories (like groceries, dining, or utilities) to earn accelerated rewards. If you unlock their Diamond Tier (₹1 Lakh/month spend), this translates to a massive 10% return.
Verdict: A targeted complement to handle the offline and utility spends that the SBI Cashback card heavily restricts.
Axis Bank Cashback: The Heavy Spender's Choice
Key Benefit: Features a tiered system that rewards high-volume shoppers with 7% cashback on online spends above ₹40,000. It also offers a higher ₹4,000 monthly cap on accelerated rewards compared to SBI's ₹2,000 cap.
Verdict: A definitive switch if you consistently spend more than ₹40,000 online every month.
Final Verdict
The SBI Cashback Credit Card continues to deliver strong value despite the April 2026 changes. Its flat 5% cashback across online merchants remains unmatched in terms of flexibility.
However, the reduced cap and expanding exclusions mean it is no longer a “one-card solution.” Pairing it with complementary cards is now essential for maximising returns.
For most users, this is still one of the most reliable cashback cards available in India.
Final Rating: 7 / 10
Best For: Online shoppers spending ₹20K–₹40K/month
Recommended Pairing: Equitas Selfe + Amazon Pay ICICI
Disclaimer
Card features, fees, and cashback terms are subject to change. Always verify the latest details on the official SBI Card website before applying. CreditKeeda may earn referral commissions from approved applications.