
 Creditkeeda

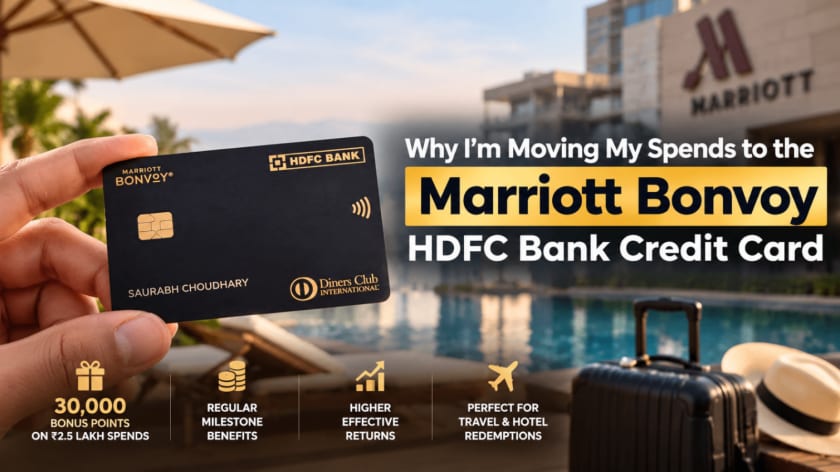
For the next two months, I’m moving a large chunk of my spends to the Marriott Bonvoy HDFC Bank Credit Card.
Yes, even though I have cards like the HDFC Diners Club Black Metal and Axis Magnus for Burgundy (M4B) that can offer excellent returns.
The reason is simple: there is currently a spend-based offer on the Marriott Bonvoy HDFC Bank Credit Card that changes the maths considerably.
Combine that with the card’s regular milestone benefits, and this is probably one of the better opportunities I’ve seen recently to build a sizeable Marriott Bonvoy balance.
The Current Marriott Bonvoy HDFC Spend Offer
HDFC Bank is running a targeted spend-based offer on the Marriott Bonvoy HDFC Bank Credit Card from 1 October to 30 November 2026.
Eligible Spends | Bonus Marriott Bonvoy Points |
|---|---|
₹1.5 lakh | 15,000 points |
₹2.5 lakh | 30,000 points |
The maximum benefit is 30,000 bonus Marriott Bonvoy points. The milestones are not cumulative, so spending ₹2.5 lakh gets you 30,000 bonus points, not 45,000.
Registration is mandatory and needs to be completed by 10 November 2026.
Register for the Spend Offer
Register for the Marriott Bonvoy HDFC Spend Offer
If you don’t already have the card:
Apply for the Marriott Bonvoy HDFC Bank Credit Card
Why I’m Targeting the ₹2.5 Lakh Milestone
This is where the offer becomes interesting.
The Marriott Bonvoy HDFC Bank Credit Card normally earns 2 Marriott Bonvoy points per ₹150 on eligible regular spends.
So, assuming the entire ₹2.5 lakh earns base points:
Base points: ~3,333 Marriott Bonvoy points
Offer bonus: 30,000 Marriott Bonvoy points
Total: ~33,333 Marriott Bonvoy points
If I conservatively value Marriott Bonvoy points at ₹0.50 each, those 33,333 points are worth roughly ₹16,667 to me. That works out to an effective return of around 6.7%.
At ₹0.60 per point, the value becomes roughly ₹20,000, or around 8%.
Of course, Marriott Bonvoy points don’t have a fixed cash value. Your actual return depends entirely on how and where you redeem them.
But I regularly stay at Marriott properties and already have future Marriott redemptions in mind, so these points have genuine utility for me.
Why Not Put These Spends on DCB Metal?
Diners Club Black Metal is still one of my primary cards.
On regular spends, DCB Metal earns 5 Reward Points per ₹150, effectively around 3.33% when redeemed at ₹1 per point towards eligible travel bookings.
That’s an excellent base return.
But ₹2.5 lakh of standalone spending doesn’t get me to DCB Metal’s ₹4 lakh quarterly milestone.
So if I don’t specifically need those spends to complete my DCB Metal milestone, earning roughly 33,333 Marriott Bonvoy points from the same ₹2.5 lakh currently makes more sense for me.
This doesn’t make Marriott a better card than DCB Metal. It simply makes it the better card for these spends, during this offer period.
What About Axis M4B?
M4B is a slightly different comparison.
It can generate exceptional returns on certain spends, particularly where accelerated rewards are involved. I’m not going to move high-return spends from M4B to Marriott just for the sake of completing this offer.
Instead, I’ll move spends where Marriott currently gives me a better effective return.
Once the ₹2.5 lakh target is complete, I can go back to optimising spends across DCB Metal, M4B and other cards.
The Bigger Reason: Marriott Points Are Harder to Accumulate
This is probably the biggest reason I want to maximise this offer.
Marriott Bonvoy points aren’t particularly easy to accumulate in India.
With HDFC Reward Points, I have multiple ways to build a meaningful balance through regular spending, milestones and SmartBuy.
Marriott is different.
Outside Marriott stays, credit-card spending, occasional transfer bonuses and buying points, there aren’t many easy ways to consistently generate large quantities of Bonvoy points.
So when I can generate 30,000 bonus Bonvoy points from spending I was going to do anyway, I see considerable value in taking advantage of it.
Especially because I actually use Marriott points.
Marriott Redemptions Are Where the Value Comes In
My intention isn’t to accumulate Marriott points indefinitely. I have Marriott stays and redemptions planned, and that’s ultimately where I want to use this balance.
Marriott Bonvoy also offers its Stay for 5, Pay for 4 benefit on eligible award stays. When redeeming points for five consecutive nights, the lowest-priced night in points is effectively free.
That can significantly improve the value of a large Bonvoy balance.
It’s also why I don’t like assigning a blanket value of ₹0.50 or ₹0.60 to every Marriott point. Some redemptions will give you less, while good redemptions can give you considerably more.
There’s Another Milestone Running in Parallel
The spend offer isn’t the only thing I’m considering.
The Marriott Bonvoy HDFC Bank Credit Card also offers a 15,000-point Free Night Award at each of these annual spend milestones:
₹6 lakh: 1 Free Night Award
₹9 lakh: another Free Night Award
₹15 lakh: another Free Night Award
So the ₹2.5 lakh I spend during this promotional period can potentially serve two purposes:
Unlock the 30,000-point promotional bonus while also moving closer to the card’s regular annual spend milestones.
That makes the overall proposition much more interesting than looking at the 30K bonus in isolation.
How I Plan to Hit ₹2.5 Lakh
I’m not going to manufacture spends just to earn Marriott points. The plan is to redirect expenses that are already coming up, with a particular focus on spends that normally earn little or nothing on my other cards.
A major one for me is gold/jewellery. I already have some planned purchases, which should take care of a meaningful portion of the milestone while also earning regular Bonvoy points.
But the more interesting opportunity is with normally excluded or zero-reward spends.
Think tax payments, rent, education fees, fuel and similar categories. Many of these either earn no rewards or are excluded from the regular rewards programme on premium cards.
Here’s the important distinction: the terms of this promotional offer are different from the card’s regular rewards terms.
For this ₹1.5 lakh/₹2.5 lakh spend offer, EMI transactions and wallet loads are excluded. That means a transaction can count towards the promotional milestone even if it doesn’t earn regular Marriott Bonvoy points.
And that changes the maths considerably.
If I use ₹2.5 lakh of spends that would otherwise earn little or nothing and unlock 30,000 bonus Bonvoy points, that’s around ₹15,000 in value at my conservative ₹0.50-per-point valuation.
That works out to an effective return of roughly 6% even without earning a single base point.
So my plan is simple: prioritise normally low or zero-reward spends, add my planned gold/jewellery purchases and regular spends where needed, and cross ₹2.5 lakh without spending anything I wasn’t already going to spend.
I’d much rather use this offer to extract value from spends that normally earn me nothing than divert ₹2.5 lakh of high-reward spending away from DCB Metal or M4B.
For me, that’s probably the most attractive part of this offer.
The Bottom Line
This is a good example of why I don’t believe there is one permanent “best credit card.”
DCB Metal can be better for one transaction. M4B can be significantly better for another.
And for the next ₹2.5 lakh of my spending, the Marriott Bonvoy HDFC Bank Credit Card currently makes a lot of sense.
If most of it is regular reward-earning spend, I could end up with around 33,000+ Marriott Bonvoy points. If I use excluded or zero-reward categories instead, I may earn fewer base points, but the 30,000-point promotional bonus is still the main attraction.
On top of that, these spends move me closer to the card’s regular annual milestones, and I’m accumulating points in a programme where I already have redemptions planned.
That’s enough reason for me to temporarily move a large chunk of my spending to Marriott.
But there’s one important rule: don’t spend ₹2.5 lakh just because there’s an offer.
If you already have those expenses coming up, optimise them.
That’s where credit-card rewards actually make sense.
Apply for the Marriott Bonvoy HDFC Bank Credit Card
If you’re planning to get the card:
Apply for the Marriott Bonvoy HDFC Bank Credit Card
Already have the card?
Register for the October-November Spend Offer
Credit-card offers, reward structures and milestone terms can change. Check the applicable offer terms before making spends solely to achieve a milestone.